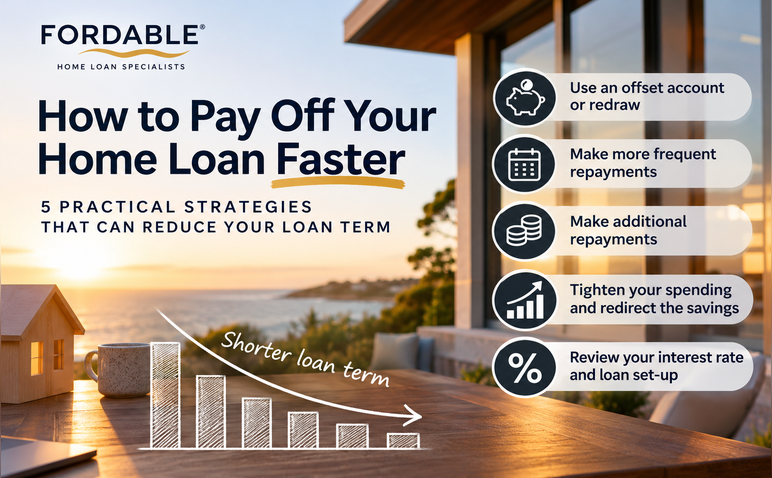
How to Pay Off Your Home Loan Faster: 5 Practical Strategies
A lower home loan interest rate can help reduce mortgage costs, but it is not the only way to get ahead on your home loan. How you use your savings, organise repayments and manage household spending can also make a difference.
When I review home loans with Fordable clients, I discuss practical ways they may be able to reduce interest and, where appropriate, shorten the time it takes to repay their mortgage. Here are five strategies worth considering.
1. Put your savings to work with an offset account or redraw facility
Interest on most Australian home loans is calculated daily. That means the balance used to calculate interest matters every day, not just on repayment day.
An eligible 100% offset account is a transaction account linked to your home loan. If you owe $700,000 and maintain $40,000 in a correctly linked 100% offset account, interest is generally calculated on $660,000 while that balance is maintained. Your savings remain in a separate account, subject to the account terms.
A redraw facility works differently. You make extra repayments directly into the loan and may be able to access some of those additional repayments later, subject to lender rules, limits and possible fees.
Both approaches can reduce interest, but they are not interchangeable. Offset products can carry higher rates or fees, while redraw access may be restricted. If the property is or may become an investment, discuss potential tax consequences of redraw and mixed-purpose borrowing with a qualified tax adviser.
Practical tip: Check that your offset account is actually linked to the correct loan and functioning as expected, especially after a refinance or product change.
2. Consider weekly or fortnightly repayments
Changing repayment frequency can help you get money into the loan earlier. However, weekly repayments are not automatically better simply because home loan interest is calculated daily. The amount paid across the year and the timing of those payments both matter.
Here is the key difference: if your monthly repayment is $3,000 and you pay $1,500 every fortnight, you pay $39,000 over 26 fortnights rather than $36,000 across 12 monthly payments. That is the equivalent of one extra monthly repayment each year.
By contrast, if your lender simply converts the annual minimum of $36,000 into 26 fortnightly instalments, the fortnightly amount is about $1,384.62. You would not be making the same additional annual repayment.
Some lenders calculate or administer repayment frequencies differently. Ask your lender or broker to confirm the annual amount, payment dates and whether the change is expected to reduce your loan term.
3. Make extra repayments, even if you start with $50
An additional $50 each repayment may seem modest, but consistent extra principal repayments can reduce the balance on which interest is charged and may shorten a principal-and-interest loan term.
For example, an extra $50 each fortnight is $1,300 over 26 fortnights, before allowing for any interest savings. The longer-term benefit depends on your loan balance, interest rate, remaining term and repayment arrangements.
You might also consider directing some of a bonus or other surplus cash towards your home loan, provided you retain appropriate funds for bills and emergencies.
Check your loan conditions first. Fixed-rate loans can restrict extra repayments or charge fees, and not every lender treats additional payments in the same way.
4. Review household spending and redirect what you can afford
This is the lever that can be easiest to overlook. A household can have a strong income and still find that everyday spending absorbs most of its available cash.
Review recurring subscriptions, insurance renewals, unused memberships, takeaway meals and discretionary purchases. The aim is not to eliminate the things you value. It is to understand where your money goes and decide whether some of it could work harder against your mortgage.
For instance, freeing up $25 per week creates $1,300 over 52 weeks that could potentially be directed into an offset account or additional repayments. The interest benefit will depend on when and how those funds are applied.
For business owners and executives with variable income, it can also help to plan how irregular bonuses or distributions will be handled before they arrive. Keep personal and business cash-flow obligations separate and obtain accounting advice where appropriate.
5. Review your interest rate and consider keeping repayments unchanged
A lender-approved interest rate reduction may lower your required repayments or the interest charged. If your repayments reduce and you can comfortably afford to keep paying the previous amount, the difference may help reduce principal faster on an eligible principal-and-interest loan.
For example, if your required repayment falls by $120 a month but you continue paying the former amount, you may be directing an additional $120 each month towards your loan, subject to how your lender applies repayments.
A rate discount is not guaranteed. The result depends on lender policy, the product, your circumstances and any associated fees. If refinancing is being considered, compare the full costs, loan features, remaining term and any break or switching charges. Extending the loan term can increase total interest even when the interest rate is lower.
Which strategy should you start with?
The right starting point depends on your cash reserves, loan features, repayment flexibility and household commitments. You do not need to use every strategy at once.
- Check whether your offset or redraw facility is suitable and working correctly.
- Compare the annual amount you pay under monthly, fortnightly and weekly repayment options.
- Choose an affordable extra repayment amount and review it periodically.
- Look for manageable spending changes without compromising essential expenses.
- Review your interest rate, fees and loan term before making changes.
Frequently asked questions
Does paying weekly instead of monthly pay off a mortgage faster?
It can, depending on payment timing and whether you pay more over the year. Paying one-quarter of a monthly repayment every week, or half every fortnight, usually means a higher annual total than 12 monthly repayments. Merely changing frequency while keeping the annual amount the same may produce a smaller benefit.
Is an offset account better than redraw?
Neither is universally better. An offset account keeps money in a separate account and may be useful where you want ready access to cash. Redraw relates to extra money paid into the loan and is subject to lender access conditions. Compare fees, rates, access and any tax implications with appropriate professionals.
Will a lower interest rate automatically shorten my loan?
Not necessarily. If the lender reduces your minimum repayment, your loan may remain on its existing schedule. Maintaining a higher repayment, where permitted and affordable, can help reduce principal sooner. Confirm the lender’s repayment treatment and remaining loan term.
Make your next home loan review count
A mortgage review should consider more than the advertised rate. It is also an opportunity to examine offset and redraw features, repayment frequency, additional repayments, fees and the remaining loan term.
At Fordable, we help Australian homeowners and property investors review their mortgage arrangements and compare suitable lending options against their credit needs.
Would you like to check whether your current home loan is working as effectively as it could? Contact Fordable to arrange a home loan review.
What is one change you have made that helped you get ahead on your mortgage — an offset account, more frequent repayments, extra payments or a tighter household budget? We would be interested to hear your experience.
Credit Representative 513965 is authorised under Australian Credit Licence 389328. Your full financial needs and requirements need to be assessed prior to any offer or acceptance of a loan product.
This article provides general information about home loans, not personal financial, tax or accounting advice. Features, fees and repayment rules vary by lender. Outcomes depend on individual circumstances and loan terms.